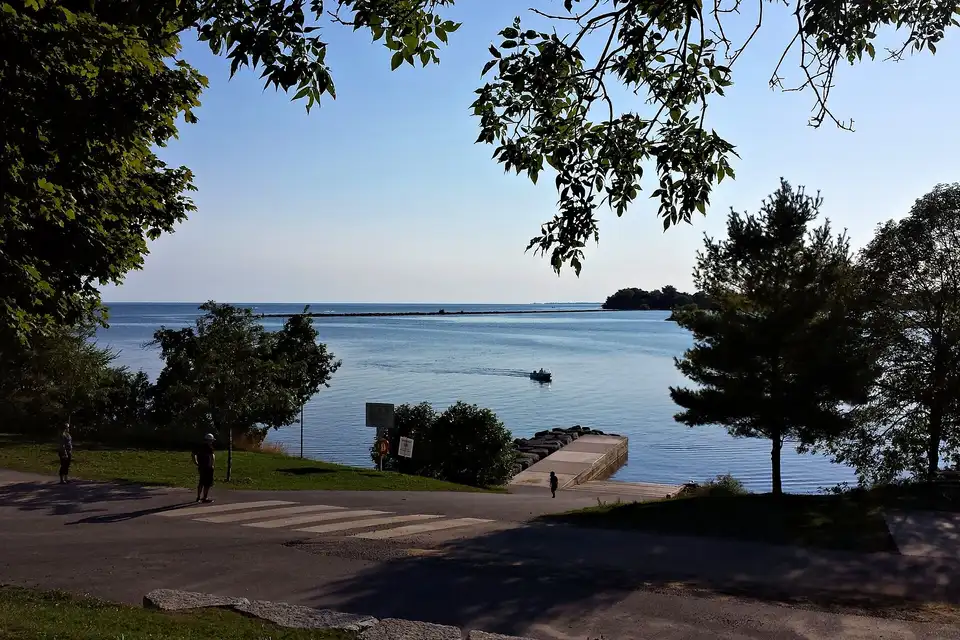

ReverseMortgageKingston.ca looks at reverse mortgages for homeowners 55 and older in Kingston’s west end. Here, that means the suburbs west of Cataraqui Creek and south of Highway 401. Until January 1, 1998, this land was Kingston Township, which then joined the old City and Pittsburgh Township (Utilities Kingston).
The west end at a glance
Bayridge, Westbrook and Cataraqui North make up most of the west end’s housing. Collins Bay, Reddendale and Polson Park are closer to the lake. Most homes are detached houses and townhouses. The busiest roads include Bath Road, Front Road and Taylor-Kidd Boulevard.
Across the whole city, 48.0% of occupied homes were single-detached houses in the 2021 Census (Statistics Canada). Houses and townhouses both qualify with reverse mortgage lenders.
Amherstview is the next community past Collins Bay, but it belongs to Loyalist Township. The Kingston tax rates and City programs below don’t apply to a home there.
What a west-end house or townhouse could qualify for
A west-end homeowner could qualify for roughly 46% to 60% of the home’s appraised value, depending on the youngest owner’s age. No price figure is published for the west end alone, so the table below uses the Kingston-and-area benchmarks for September 2026 (KAREA via CREA).
| Youngest owner | Detached at $566,800 | Townhouse at $403,300 |
|---|---|---|
| 65 (up to 50.55%) | up to about $286,500 | up to about $203,900 |
| 70 (up to 52.85%) | up to about $299,600 | up to about $213,100 |
| 75 (up to 57.75%) | up to about $327,300 | up to about $232,900 |
These are ceilings on the highest-lending products, not quotes. Your own home is appraised, and its value can be higher or lower than the benchmark. The Kingston reverse mortgage calculator lets you try your own age and value.
The ceiling covers what you already owe
This figure replaces any current borrowing on the home rather than adding to it. A mortgage or line of credit still owing gets cleared at closing from this amount.
West end property tax: the fire-area rate
Kingston’s residential tax rate depends on the property’s fire area, because the City sets fire charges by area. In 2026, the West fire area rate is 1.533257% of assessed value, against 1.605435% in the Central area; your tax bill shows which area your home is in (By-law 2026-54).
That works out to about $1,533 per $100,000 of assessment in the west end, and about $1,605 in the Central area. For example, a home assessed at $350,000 would pay about $5,366 a year in the West area and about $5,619 in the Central area.
Assessments in 2026 are still based on January 1, 2016 values, so the assessed figure on your bill can be quite different from what the home would sell for today (City of Kingston tax bill insert). The average Kingston residential bill in 2026 is $5,113.
Tax relief comes with conditions
If you are 65 or older and receive the Guaranteed Income Supplement, the City’s tax deferral lets you put off up to 50% of the year’s tax, to a maximum of $1,000 (City of Kingston). A lien is registered, and the deferred amount is repaid when the home is sold. The guide to Kingston property tax for seniors covers every program.
With a reverse mortgage, the property tax bill is still yours, along with home insurance and upkeep.
Room for family on a west-end lot
Most west-end lots are urban, so the City’s rules for an additional residential unit, such as a basement suite or a garden suite, can apply. The City allows these units on most properties except rural ones, with some limits in certain sewer areas (City of Kingston).
The City’s incentive offers a forgivable loan of up to $40,000 for a detached unit or $30,000 for an interior one. New applications now go to a waitlist, and only projects with a building permit issued by December 1, 2026 will be considered (City of Kingston). The City secures loans of $5,000 or more with a second mortgage on the home, so mention any plan for the incentive at the start.
Home equity can pay for the unit itself. The page on building an additional residential unit in Kingston explains how that works.
An illustrative west-end example
For example, an illustrative widow of 75 owns a freehold townhouse in Westbrook. For this example the home appraises at $403,300, the Kingston-and-area townhouse benchmark for September 2026.
At 75, the top of the age range is up to 57.75% of the home’s value, or about $232,900. She still owes $40,000 on a HELOC (home equity line of credit), which is paid off first. That leaves up to about $192,900.
She takes $50,000 to start. Part pays for a new furnace and roof, and part is set aside for paying for home care in Kingston later on. Interest is charged only on the money she takes, and she has no required monthly mortgage payments.
Her son is copied on every email. Other common uses for the money are repairs to a Kingston home and giving family a living inheritance.
How help reaches a west-end homeowner
Help reaches you by email, phone and video call. After the free estimate, every lender is compared for your home, and the best deal for your situation and goals arrives in your inbox. You get a recommendation based on your situation, even if it’s not a reverse mortgage.
An appraiser walks through the home once. The other in-person step is independent legal advice with your own lawyer, which usually costs about $800 to $1,200 in Ontario.
For programs and company nearby, the Seniors Association Kingston Region runs activities in the west end as well as downtown. If a move is on your mind instead, the cost of downsizing in Kingston sets out what selling and buying involve.
Communities in Kingston's West End
Wherever your street is in Kingston's West End, the lenders and the steps are the same. These are some of the communities included.
- Bayridge
- Westbrook
- Collins Bay
- Reddendale
- Polson Park
- Cataraqui North
Places you'll know
- Lake Ontario Park
- Cataraqui Creek
- Collins Bay Institution
- Bath Road
- Front Road
- Taylor-Kidd Boulevard
Getting help from Kingston's West End
West-end owners deal with Richard Hopkins, Mortgage Broker, by email, phone and video call; you never need to visit an office, and a son or daughter can be copied in. An appraiser comes out to the house itself. Apart from that, the only face-to-face step is independent legal advice at a lawyer's office you pick.
What homes in Kingston's West End are worth
No west-end figure is published. For Kingston and area, the September 2026 benchmark was $566,800 for a detached home and $403,300 for a townhouse.
Source: Kingston and Area Real Estate Association via CREA, September 2026
What Kingston's West End owners use the money for
- Home repairs and accessibility: Use your home's value to pay for roofs, windows, furnaces and accessibility changes, with no required monthly mortgage payments.
- Helping your children now: How Kingston parents can use their home's value to help adult children now, with the whole family copied on every email.
- Garden suites and second units: Kingston's rules for second units and garden suites, the City's incentive loans, and how your home's value can pay for the build.
- Paying for care at home: Pay for extra help at home from your home's value, as a lump sum or regular deposits, with no required monthly mortgage payments.