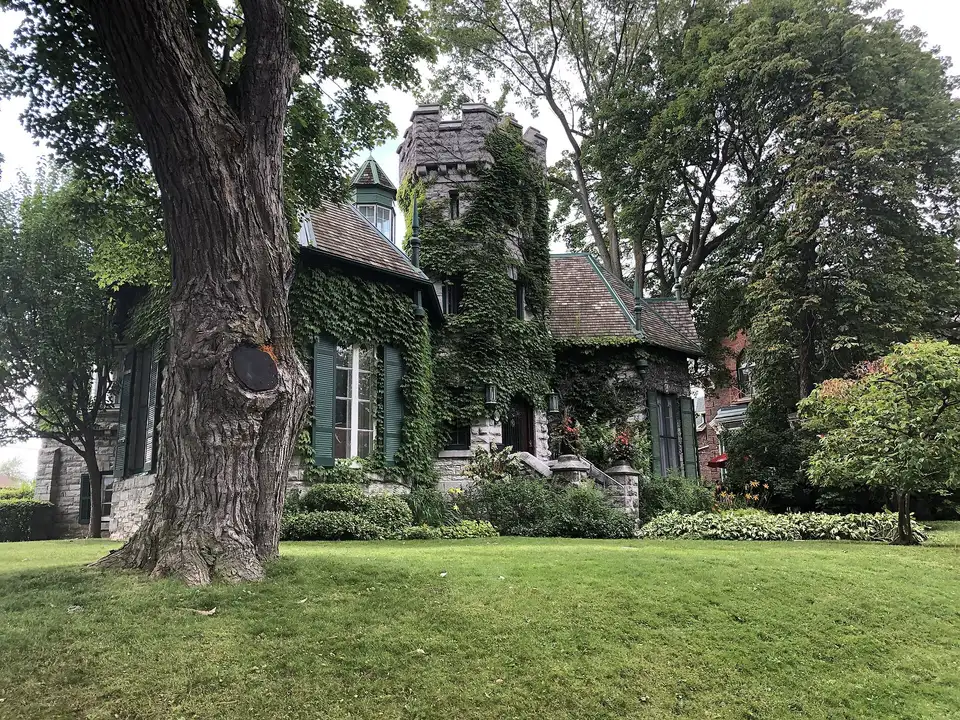

ReverseMortgageKingston.ca looks at how a reverse mortgage works on a heritage home in Kingston, from limestone houses downtown to the older streets of Barriefield. Homes like these often come with larger repair bills, and the City’s heritage programs pay for only part of them. A reverse mortgage can cover the rest, with no required monthly mortgage payments.
Kingston’s three heritage conservation districts
Kingston has three heritage conservation districts, and together they protect more than 700 properties (City of Kingston).
- Old Sydenham: about 550 properties, designated in 2015. It is roughly bounded by Johnson Street, Barrie Street, King Street East and Lake Ontario.
- Market Square: in the downtown core, established in 1985.
- Barriefield Village: beside the Cataraqui River, across from Fort Henry, established in 1981. The page on reverse mortgages in Kingston East covers that side of the river.
Individual homes outside these districts can also be designated under the Ontario Heritage Act.
What designation means for an owner
A heritage permit may be needed before you change the outside of a home in a district. Routine maintenance needs no permit. City staff approve minor alterations, while larger projects go to the Heritage Properties Committee and then to Council.
Designation doesn’t require you to restore the home beyond normal property standards. It also gives the public no right to enter your property.
Older homes cost more to keep up
About one in five Kingston homes was built in 1960 or earlier. In the 2021 Census, 21.5% of occupied homes in the City of Kingston fell in that group (Statistics Canada, 2021 Census).
Older stone homes tend to cost more to maintain. Windows, masonry and roofs are the usual large bills, and work on the outside of a home in a district may need a permit first. The page on paying for home repairs in Kingston covers repairs on any kind of house.
The City’s heritage money
Heritage Property Grants
The grant pays 50% of a project’s cost, to a maximum of $2,000 a year, for eligible properties (City of Kingston). Grants go out first-come, first-served, and an owner can apply every two years.
Heritage Property Tax Refund
The refund is 40% of the property taxes, up to $5,000 or the total cost of approved maintenance work. An owner can apply once every three years. The home must be designated under the Ontario Heritage Act and have an easement or preservation agreement, and applications are due by the last business day of February after the tax year.
Where these programs stop
A $2,000 grant covers only part of a large job such as a new roof or full window restoration. The guide to Kingston property tax help for seniors covers the City’s other tax programs.
How a reverse mortgage works on a heritage home
A heritage designation does not stop a home from qualifying. The usual rules apply: every owner on title is 55 or older, and you live in the home for at least half of every year.
Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada, older stone homes included. In his first email you see the amount you could get and which lenders suit the house, and he asks how much you need. You get a recommendation based on your situation, even if it’s not a reverse mortgage.
What the appraiser looks at
The appraiser values a heritage home on its condition and on recent comparable sales. Condition is part of the lender’s approval, and older homes are more likely to have repairs noted in the appraisal.
Lenders can sometimes keep part of the money back for a noted repair, paying it out when the job is done. This is known as a holdback. For a house in poor shape, a short private mortgage sometimes comes first, and the reverse mortgage replaces it later.
An illustrative example on a $566,800 home
Take an illustrative homeowner, aged 75, in a detached stone house valued at $566,800. That is the September 2026 single-family benchmark for Kingston and area (KAREA via CREA, September 2026). At 75, her ceiling is up to 57.75% of the value, which works out to about $327,300.
She owes nothing on the home in this example, so nothing comes off the top. A mason’s quote for repointing plus new storm windows comes to $70,000. This amount is only an example. She also applies for the City’s heritage grant.
She takes $70,000 and doesn’t borrow the other $257,300 or so. Interest is charged only on the $70,000. The Kingston reverse mortgage calculator shows your own ceiling, then charts home value, loan and equity across 15 years.
Costs, payments and protections
Five-year fixed rates advertised by the lenders were between 6.23% and 6.49% on October 31, 2026. Plan on about $2,000 to $3,500 in one-time costs. The money goes to the appraisal, a set-up fee charged by the lender, and roughly $800 to $1,200 for independent legal advice from your own lawyer. The guide to reverse mortgage cost in Kingston lists each item.
Richard’s help costs you nothing, since the brokerage is paid by the lender after funding. No monthly mortgage payment is required, but property tax, home insurance and upkeep remain yours.
Interest is added to the balance over time. Home values often grow too, which can make up some or all of the interest. On average, Canadian borrowers keep about half of their equity. The guide to Kingston home prices shows recent values.
You can never owe more than your home is worth when the mortgage comes due. Keep the taxes, insurance and upkeep current and that promise applies. This protection is typically called the no negative equity guarantee.
You can repay early at any time, though a charge usually applies in the first years. Some lenders let you prepay up to 10% of the balance a year without a charge.
Some owners of larger heritage lots also look at adding a second unit; the page on building an additional residential unit in Kingston covers the City’s rules. If the money is meant for your children, see giving a living inheritance in Kingston.
What Richard Hopkins handles for you
- Estimates how much your heritage home could provide
- Compares every reverse mortgage lender in Canada for an older home
- Sends, by email, the best deal for your home once every lender is compared
- Explains how the appraisal treats an older stone house
- Explains how repairs noted in the appraisal can be handled
- Explains using City heritage grants alongside a reverse mortgage
- Copies your family on every email, if you want them involved
- Follows each step from the estimate through to closing
Your choices next to each other
| Question | City heritage grant | Heritage tax refund | Reverse mortgage |
|---|---|---|---|
| How much | Up to $2,000 a year, 50% of the project cost | 40% of taxes, up to $5,000 | Up to 57.75% of the home's value at 75, less what you owe |
| Who qualifies | Owners of eligible heritage properties | Designated homes with an easement or preservation agreement | Every owner 55 or older, living in the home |
| Repayment | None, it is a grant | None, it is a refund | Due on a sale, a permanent move, or the last borrower's death |
| How often | Apply every two years | Once every three years | One mortgage, with later draws at some lenders |
| What it can pay for | Approved heritage projects | Money back on property taxes | Any purpose, including work the City programs don't cover |
Kingston guides that go deeper
- Kingston Property Tax for Seniors: Rates, Due Dates and Help in 2026
- Kingston Home Prices in 2026 and What They Mean for a Reverse Mortgage
- What Does a Reverse Mortgage Cost in Kingston?
Sources
Figures checked October 16, 2026.